Credit Scoring Is Changing. What Does That Mean for North County Homebuyers?
You’ve been looking at homes in Carlsbad, Oceanside, or Vista. You have a monthly payment in mind. But before you even talk to a lender, you check your credit score and think, “I probably need to wait.”
That assumption could put your plans on hold unnecessarily.
Mortgage credit scoring is evolving, and the number you see in an app doesn’t tell you everything about your ability to qualify. If buying a home in North County San Diego is on your radar, here’s what to understand before counting yourself out.
1. There Isn’t One Credit Score Requirement for Every Buyer
It would be convenient if every mortgage came with the same qualification checklist. In practice, requirements depend on the loan program, lender, and your overall financial situation.
Your credit history matters, but so do factors such as income, existing debt, savings, and down payment. A score alone can’t tell you what a lender will approve or what your monthly payment would look like.
Many people also overestimate the credit score they need, according to consumer research highlighted by Keeping Current Matters.
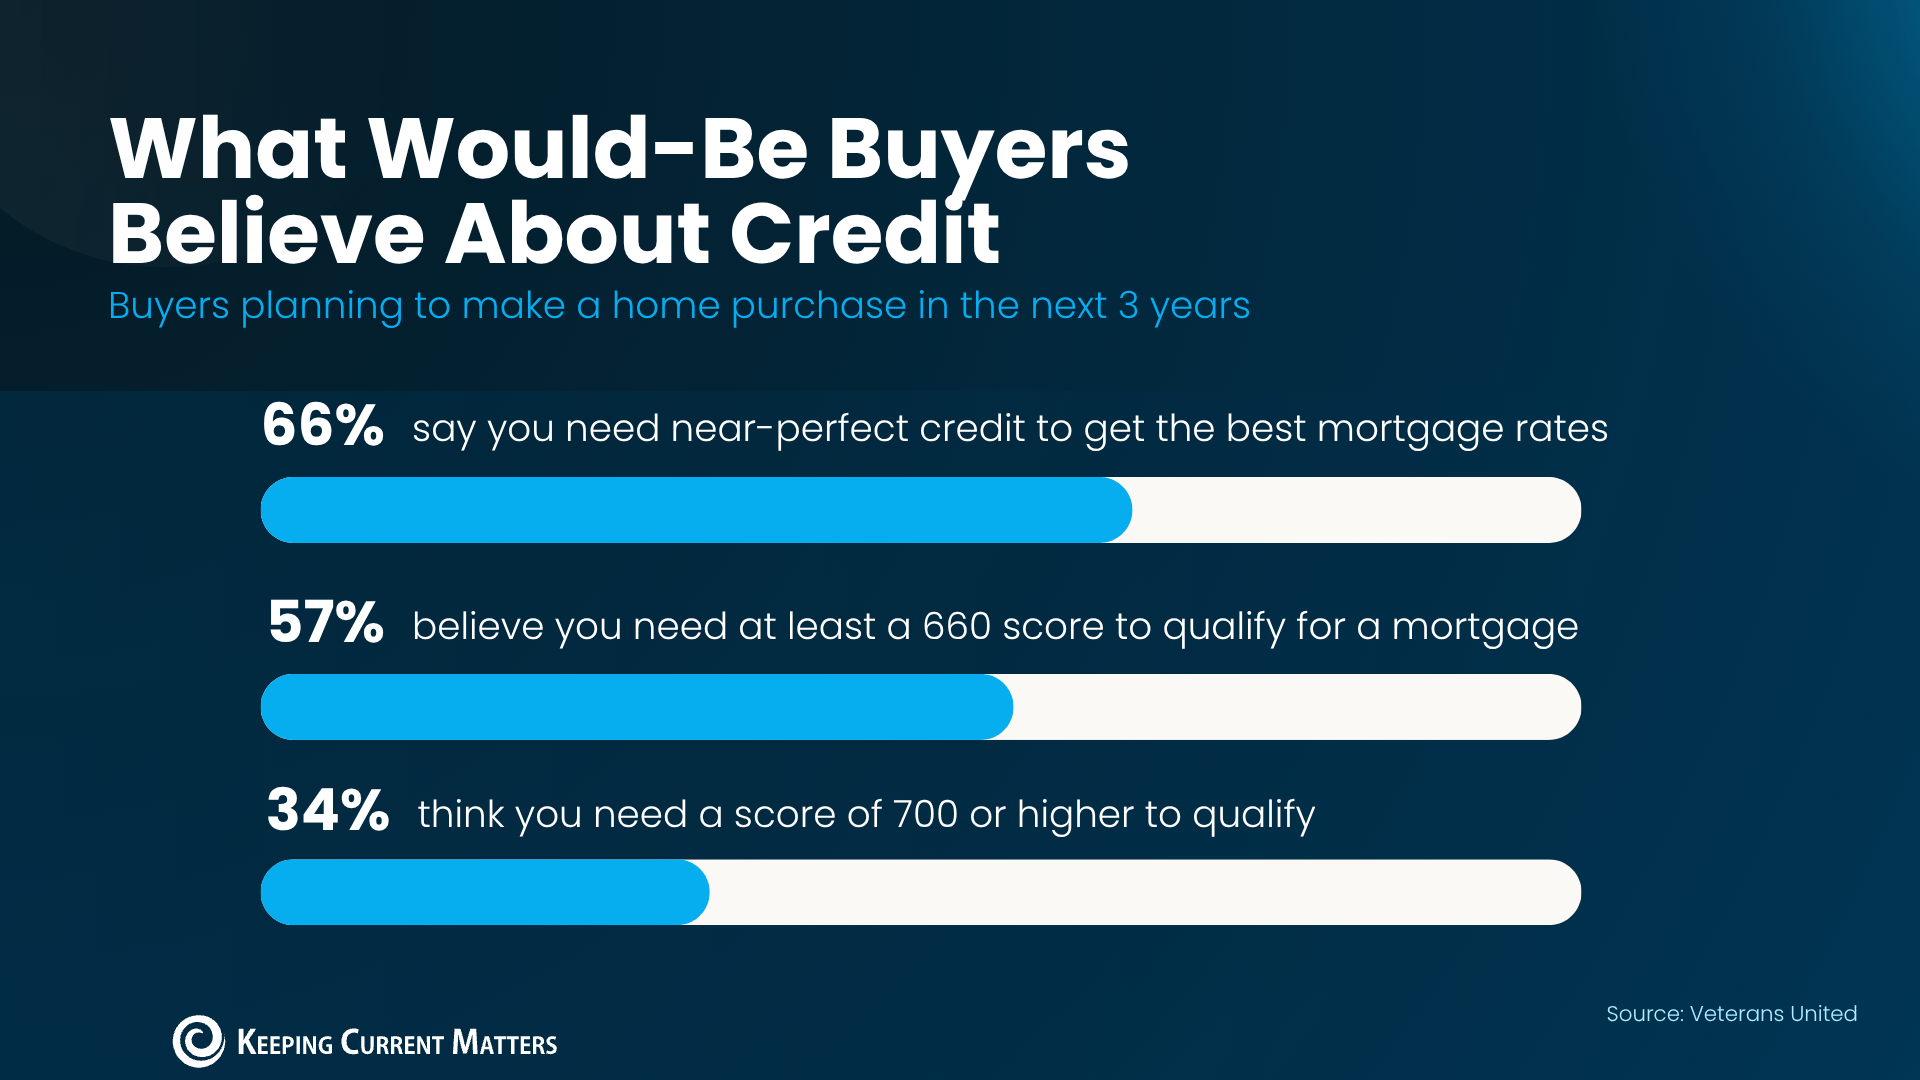
The useful next step is to get an assessment based on your actual finances. Even if you aren’t ready to buy today, that conversation can help you understand what to work toward.
2. Mortgage Lenders Have More Credit Scoring Options
For years, Classic FICO has been the standard credit scoring model for mortgages sold to Fannie Mae and Freddie Mac. Now, lenders can also use VantageScore 4.0 for eligible loans under those organizations’ requirements.
According to the Federal Housing Finance Agency, access to that option expanded to all approved lenders in September 2026. Classic FICO remains available, too.
Another model, FICO 10T, has been approved for future use, but FHFA says it is not yet eligible for loan delivery to Fannie Mae and Freddie Mac.
Why does this matter? Different models can produce different scores for the same person. Newer models can also consider additional information, including reported rent payment history.
The score in your credit monitoring app may differ from the score your mortgage lender uses. Ask which model and loan requirements apply to your application.
These changes don’t guarantee approval or a higher score. They do make it especially useful to get current information from a lender.
3. A Practical Plan Still Matters More Than Watching a Number
If you’re preparing to buy, focus on understanding your credit report and keeping your finances consistent.
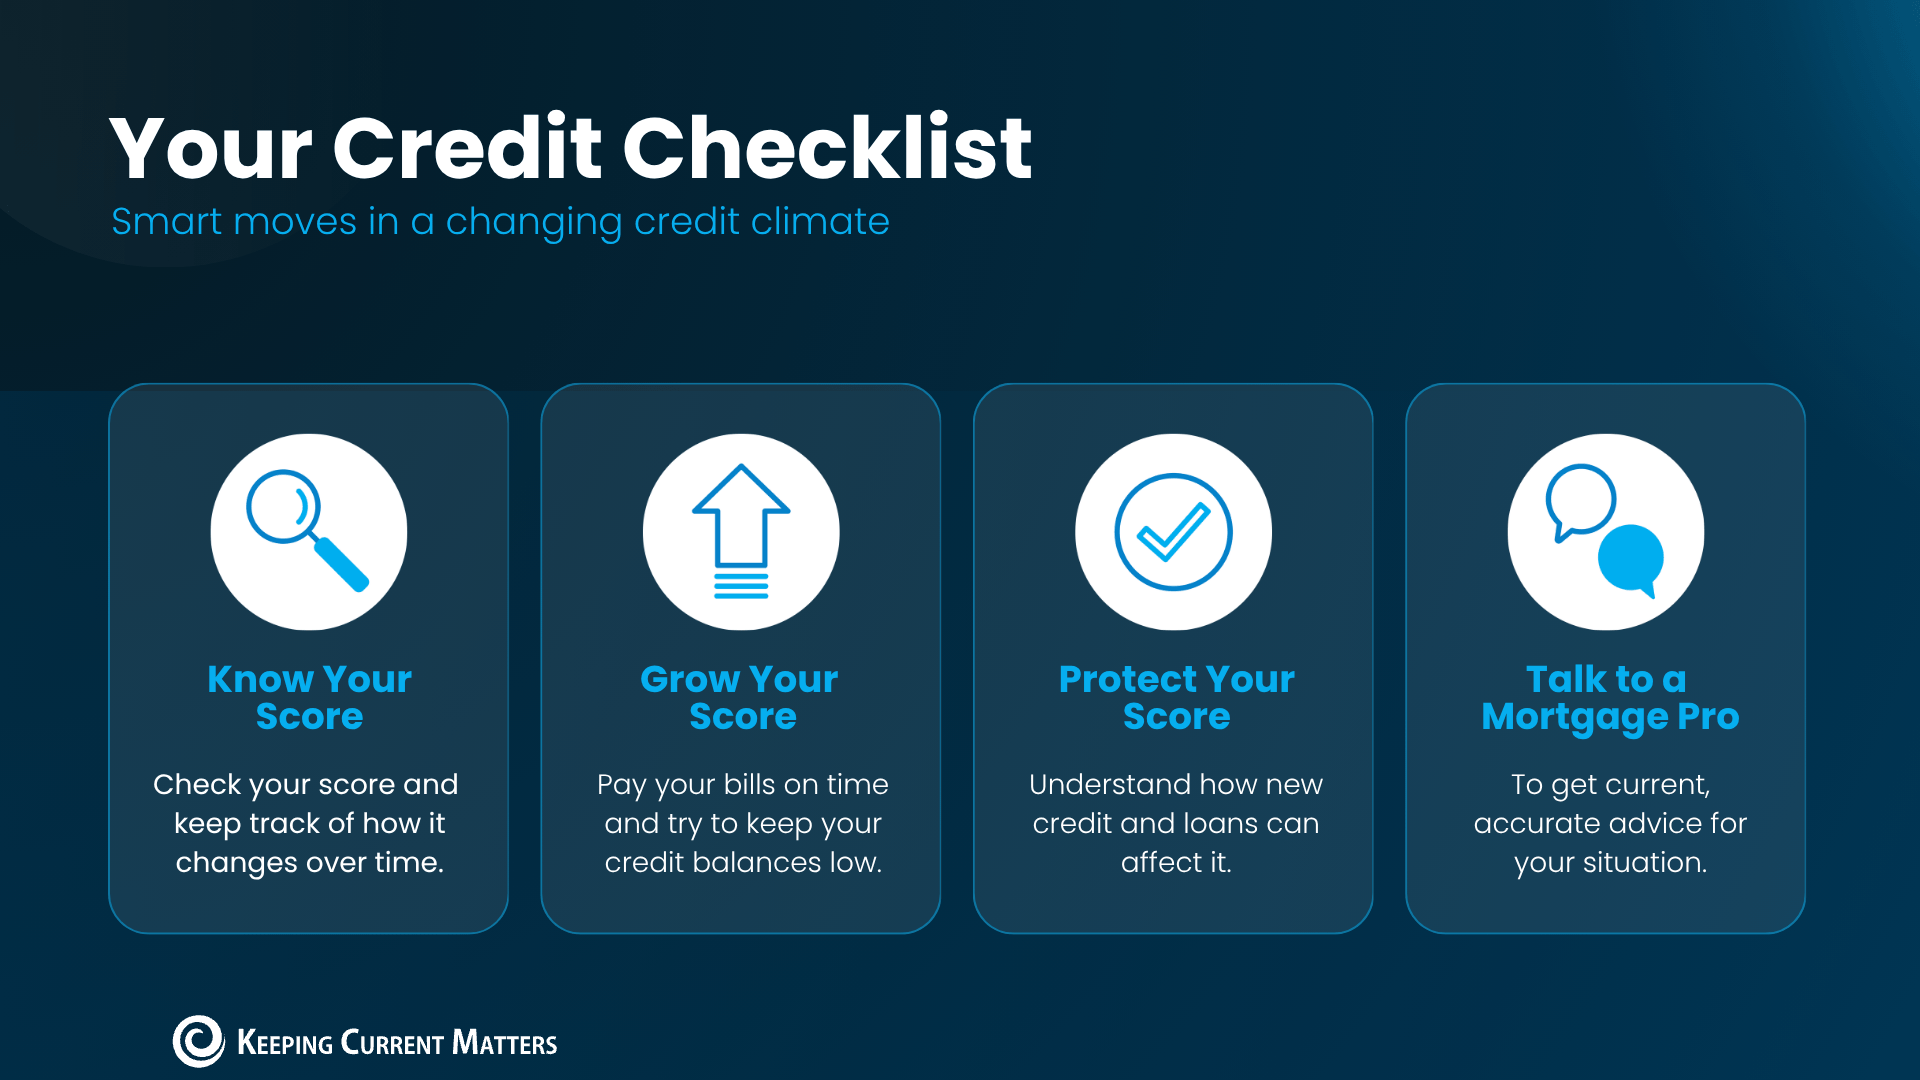
Start by reviewing your credit reports for errors and keeping payments on time. Before opening new accounts, financing a large purchase, or closing an existing account during the mortgage process, check with your lender.
You can also make your first lender conversation more productive by asking:
-
Which loan programs fit my financial situation?
-
What credit score model will you use?
-
What would help improve my application?
-
What monthly payment range should I plan around?
-
If I need more time, what should I prioritize first?
What This Means for Buying in North County San Diego
Whether you’re considering a Carlsbad condo, an Oceanside townhome, or a house farther inland, understanding your financing helps you search with a realistic budget.
You don’t need to have every detail figured out before reaching out. An early conversation can give you a clearer picture of your options and a timeline that fits your life.
Thinking about buying in North County San Diego? Contact ERA Ranch & Sea Realty | Juncal Real Estate. We’ll help you explore local neighborhoods and connect you with a mortgage professional to understand your next steps.
Sources: Keeping Current Matters, October 30, 2026 and Federal Housing Finance Agency: Credit Scores. Information reflects guidance available October 30, 2026. Loan eligibility and terms vary by lender, program, and borrower.
Categories
Recent Posts

GET MORE INFORMATION
